Apply the company or LLP scope test before preparing the disclosure. Use the reporting period and organisational boundary in the accounts.
Record the entity type, group position, financial year, quoted status, size tests and any low-energy exemption considered.
Reconcile energy and emissions to the entities and activities covered by the directors’ report or energy and carbon report.
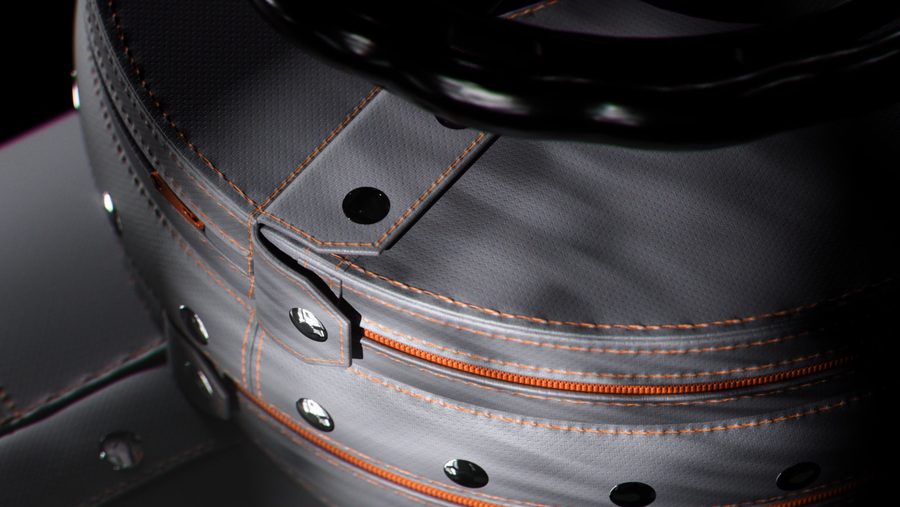
Use measured surface area, temperature and operating hours to calculate heat loss from boilers, kilns, heat exchangers, valves and pipework. Inzonex supplies removable modular insulation for equipment that requires maintenance access.
Do not add a calculated reduction to an emissions report until the reporting boundary, factor, implementation date and verification method have been approved.
Keep activity data, units, conversion-factor publication and year, methodology, exclusions, prior-year comparatives and intensity-ratio denominator.
State the measure completed during the reporting year and the evidence supporting any quantified effect. Do not insert a standard saving.
This page does not decide whether a particular organisation is in scope or verify a reported figure.